HomeBuyer Blueprint
Your strategic path to home ownership
By Team Reis: Carolyn Reis and Adriana Reis Perry, Broker/Owner and Broker Associate, Reis Real Estate & Co., Inc.
Shop with the confidence of a seasoned buyer
We built this guide to be your blueprint, with the knowledge you need to shop with the confidence of a seasoned buyer.
Expect an honest, no-nonsense breakdown of the process, because we believe your success depends on having a strategist who values integrity and transparency over a quick sale. This is your first strategic step toward securing your piece of earth, and we're honored to provide the blueprint to help you get there.
Carolyn Reis and Adriana Reis Perry
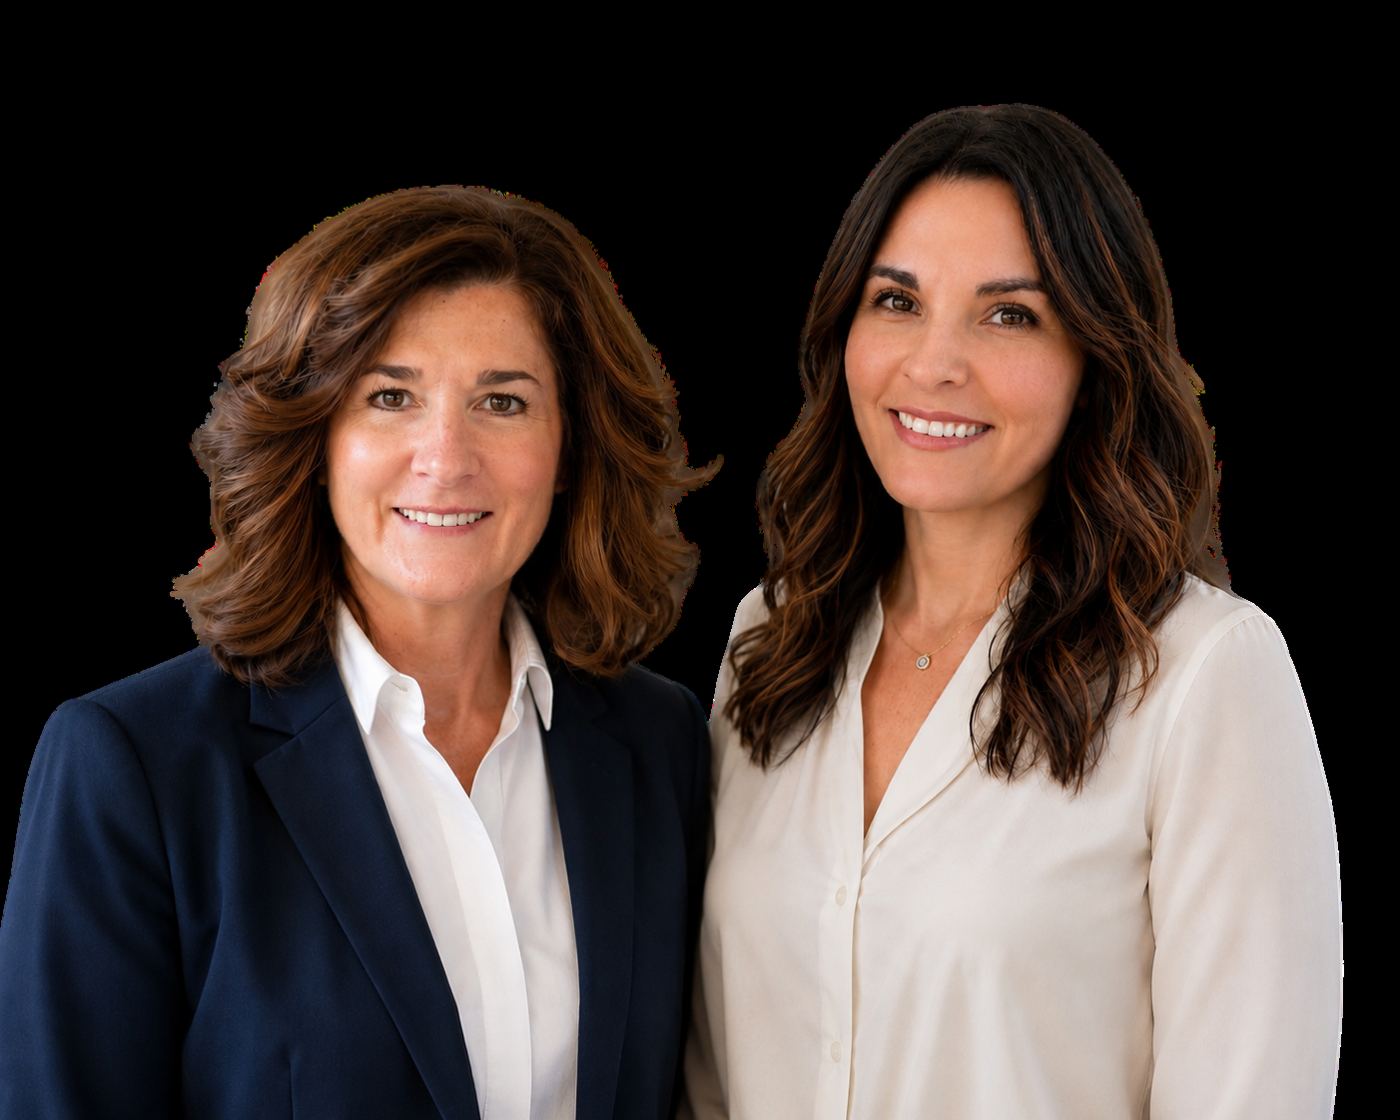
Hey there, thank you for reading!
"Home is the ultimate destination of all journeys."Sir William Temple
We're confident this guide will be a massive asset in your home buying journey.
Let us tell you a little story. Over Carolyn's 23+ years and Adriana's 12+ years, we have invested tens of thousands of hours into mastering the local real estate market. As the founder of Reis Real Estate & Co., Carolyn has personally overseen the sale of over 1,180 units and more than $94M in volume. We're not saying this to impress you. We always tell our clients that this industry is not just a career for us, it's a battle-tested obsession with helping people create generational wealth. Your home is one of the greatest treasures you can have. It's where your family comes together and where you grow.
One more thing: we didn't create this guide with ChatGPT or any other AI. The experience we've gained at Reis Real Estate isn't something a bot can write for you. Our goal is to cut out the noise so you can shop with the confidence of a seasoned investor.
Keep these in mind as you read
- You do NOT need to be a millionaire to own a property.
- You can secure a home even if your credit isn't perfect.
- The 20% down payment requirement is a myth that keeps people broke.
- The market is open to everyone, regardless of background, who is willing to follow the blueprint.
Note: We can't promise you'll build a real estate empire overnight. Every situation is unique. But these are the exact same principles we use to guide our high-level clients.
Mastering the Financial Trinity
Before we even look at a house, we have to look at the math.
We've seen every type of market cycle, from crashes to bidding wars, and the lending process today is remarkably cut and dry. There's no secret handshake to getting a loan. There's only the Financial Trinity, what the industry calls the Three C's. Lenders aren't looking to be your friend. They're looking to minimize risk. Understanding that is the difference between a denial letter and the keys to your new front door.
1. Credit
Your credit score is a snapshot of your reliability. You generally need a 620 to 640 to get in the game, but the depth of your credit history determines your interest rate, and your interest rate determines your wealth.
The breakdown you need to know
- Payment history (35%): The heavy hitter. One 30-day late notice can tank your score.
- Amounts owed (30%): Your utilization. Maxed-out cards make you look like you're struggling, even if you make six figures.
- Length of history (15%): Do not close old accounts. Age is a virtue here.
- New credit (10%): Opening three store cards to save 10% on a sofa can cost you $20,000 in higher interest over the life of your mortgage. Please don't do it.
2. Capacity
Capacity is a measure of your cash flow. Lenders want to see that you make enough to pay for the house and your existing life. We measure this with your Debt-to-Income (DTI) ratio.
- Front-end ratio: Your projected mortgage payment (including taxes and insurance) divided by your gross monthly income.
- Back-end ratio: The big one. Your mortgage payment plus every other debt on your credit report (car loans, student loans, credit card minimums).
Example: if you make $10,000 a month and your total debts (including the new house) are $4,300, your DTI is 43%. Most lenders want you at or below that number.
Just because a bank approves you for an amount doesn't mean you should spend it. We want to find your Comfort Range, so you never have to choose between your mortgage and your lifestyle. Lenders also want to see reserves after closing, usually 2 to 6 months of payments sitting in an account, paper-trailed and ready.
Here's how much home you can afford
| Annual Gross Income | Monthly Gross | Monthly Mortgage (29%) | Monthly Mortgage (41%) |
|---|---|---|---|
| $20,000 | $1,667 | $483 | $683 |
| $30,000 | $2,500 | $725 | $1,025 |
| $40,000 | $3,333 | $967 | $1,367 |
| $50,000 | $4,167 | $1,208 | $1,708 |
| $60,000 | $5,000 | $1,450 | $2,050 |
| $70,000 | $5,833 | $1,692 | $2,391 |
| $80,000 | $6,667 | $1,933 | $2,733 |
| $90,000 | $7,500 | $2,175 | $3,075 |
| $100,000 | $8,333 | $2,417 | $3,417 |
Source: David Bach, "The Automatic Millionaire"
3. Collateral
The third C is the house. The lender uses the home as a backup plan, so they need to know it's worth the investment.
The appraisal battle
Independent, third-party appraisers verify the value. In a hot seller's market, prices can move faster than the data. If you offer $500,000 and the appraiser says it's worth $480,000, there's an appraisal gap. That's where our negotiation experience matters most: we either negotiate the price down or find a smart way to bridge the gap without draining your savings.
A lender won't fund a house with a hole in the roof or a non-functioning electrical system unless you're using a specific rehab loan. The house must be safe and livable from day one, and we keep a sharp eye on this during escrow to protect your investment.
How to Apply for a Mortgage
The mortgage application, formally known as Form 1003, is the most important document in the entire deal. It tells the lender who you are, how you handle money, and why they should feel good handing you the keys. It needs to be spot-on from the second you hit send.
It covers the basics like your birth date and Social Security number, but it goes deeper: how long you've been at your job, what you do for a living, everywhere you've lived for the last two years, everything you own (assets) and everything you owe (liabilities).
You'll also answer a set of yes or no questions called Declarations, which lenders use to spot roadblocks early. For example: Have you filed for bankruptcy in the last seven years? Are you co-signed on someone else's car loan? Do you pay alimony or child support?
Most of this happens online through secure portals where you can upload documents and talk to your loan processor. Paper applications are still available if you prefer.
Pro strategies for a flawless application
The 2-Year Rule
If you haven't been at your current address or job for two years, list the previous one too. Consistency is what lenders love.
Show Off Your Assets
List more than checking: 401(k), IRAs, stocks, even life insurance with cash value. These are reserves and make you a safer bet.
Be Totally Transparent
Planning to pay off a card during the process, or expecting a raise next month? Tell your loan officer.
List All Real Estate
Land, a vacation spot, or a rental property all need to be on the application.
Unfreeze Your Credit
If a credit freeze is active, the lender can't see your score. Lift it before you finish the application.
Typos Matter
A wrong Social Security number or misspelled name can trigger a fraud alert that takes forever to fix. Double-check everything.
Keep Your Own Copy
Save the final application. It helps a lot when you refinance or buy your next property.
One at a Time
Shop lenders, absolutely. But never submit formal applications to two companies for the same house at the same time. It's a red flag and can hurt your approval.
What Documents You'll Need to Purchase
"That's a lot of paper."
"There is just too much paperwork."
We've heard it more times than we can count. And it is a lot. But when a lender is about to hand you hundreds of thousands of dollars, they need proof. The good news: with your permission, today's technology can verify your job, income, and banking info digitally, which cuts the paper down significantly. Still, if you want to move fast (and in this market, speed matters), have these documents organized and ready.
The core list
- Your identity: a clear copy of your valid driver's license or passport.
- Proof of income: pay stubs covering the last 30 days.
- The full bank picture: two months of statements, all pages, all accounts. If it says "Page 1 of 8," the lender expects Page 8 even if it's blank.
- The tax trail: W-2s and 1099s from the last two years.
- Federal returns: two years, all pages and schedules (Federal only, not state).
If you're a business owner
- Business license
- Two months of business bank statements
- K-1s or corporate tax returns
- A recent Profit & Loss (P&L) statement
Depending on your situation
- Renting now: your landlord or property manager's contact info to verify payment history.
- Already own property: recent mortgage statement, property tax bill, homeowners insurance policy, and HOA contact if you have one.
- Explaining the "blips": a brief Letter of Explanation (LOE) for recent inquiries or derogatory marks.
- Large deposits: a paper trail for any large, non-payroll deposit.
- Past bankruptcy or foreclosure: official discharge papers and supporting schedules.
- Recently sold a home: the final Closing Disclosure (CD) from that sale.
- Gift funds: a signed Gift Letter (we provide the template) and proof the money was transferred.
Do's and Don'ts of the Process
Buying a home is a high-stakes game. One wrong move can collapse the whole deal. Follow these rules religiously.
Do's
- Organize early: put your Step 3 documents in a digital folder today.
- Calculate the real cost: account for property taxes, HOA fees, and insurance, not just the mortgage.
- Save aggressively: even with low-down-payment loans, you need cash to close.
- Check your own credit: use a soft pull tool to see what lenders will see.
Don'ts
- Don't buy a car. Financing a new vehicle mid-process will wreck your DTI.
- Don't quit your job. Even a better job can cause delays if the pay structure changes.
- Don't move money. Large, unexplained deposits are a red flag.
- Don't co-sign. Co-sign your cousin's car loan and that debt is yours in the lender's eyes.
- Don't open or close credit cards or lines of credit.
Mortgage Products Explained
A mortgage is a financial product. Pick the one that fits your 5-year and 10-year plan.
Conforming Loans
The most common mortgage in the U.S.: a safe, predictable 30-year fixed loan. You can get in with as little as 3% down. Great for solid credit and a payment you can count on for 30 years.
Jumbo Loans
For high-end homes priced above federal conforming limits. Lenders are more selective, so expect a stronger credit requirement and usually a larger down payment.
FHA Loans
The "gateway" loan, backed by the Federal Housing Administration. Just 3.5% down and more forgiving on credit (sometimes as low as 580). A great way to start building equity now.
VA Loans
For those who have served. 0% down, no monthly mortgage insurance (PMI), and competitive rates. If you're a veteran or active duty, this should be your first, second, and third choice.
USDA Loans
Not just farms. Many suburban areas qualify. Like VA, 0% down for families in designated rural or less dense areas when the home and income fit the guidelines.
Adjustable-Rate (ARMs)
A lower rate for an initial period (5, 7, or 10 years). If you plan to sell or refinance before it adjusts, it can save thousands in interest.
Non-QM
For entrepreneurs, freelancers, and investors who don't "fit the mold." These lenders look at bank statements or property income instead of W-2s. Rates may be a bit higher.
The 10 Best Reasons to Buy a House
Polish your credit, apply for a mortgage, tour countless houses, save for a down payment, then move your entire life. Phew! So why do so many people do it? Because the benefits of owning a home far outweigh the temporary stress of the process.
Lock In Your Payment
Landlords can raise rent when a lease ends. With a fixed-rate mortgage, principal and interest are locked for up to 30 years, and your payments build your equity, not your landlord's.
Often Cheaper Than Renting
Despite upfront costs, the monthly cost of owning is often less than rent in many markets. A rent vs. buy calculator can show what you could save locally.
An Excellent Investment
Homes generally appreciate around 3% to 4% a year over time due to inflation and population growth, and you get a place to live while it grows.
Tax Breaks
You can generally deduct mortgage interest on loans up to $750,000 ($1 million for loans before December 15, 2017), and possibly HELOC and PMI interest used for improvements. Always check with a tax pro.
Freedom to Customize
Knock down a wall, paint a bold color, upgrade the cabinets. No landlord permission needed, and the value you add is yours.
More Privacy
Homes often offer better sound insulation than apartments, and you can add things like a fence to create your own private sanctuary.
A Built-In Rainy Day Fund
On-time payments build equity, which can act as a safety net you may borrow against for emergencies or big projects.
Stronger Community Ties
Your property taxes support local services, infrastructure, and community organizations, giving you a real stake in your area's success.
A Secure Retirement
Hold a home long term and you can sell and downsize later, or rent it out for steady income.
It's Yours!
Renters can be displaced when a landlord sells. As long as you own your home, no one can tell you to leave.
Checklist for First-Time Buyers
Cleaning Up Your Credit Score
If your credit needs work, we don't ignore it, we fix it. Lenders want to see that you're a low-risk bet.
1. Dispute errors
Credit reports often contain mistakes. Challenge any inaccuracies.
2. Raise limits
Ask your card company for a limit increase. It lowers your utilization ratio right away.
3. On time, every time
Set every bill to auto-pay.
4. Strategic payoffs
Focus on revolving debt (credit cards) first.
Do You Have the Perfect Real Estate Agent?
"They take people to see houses until they find one they love. Then they make wedding plans!"
Buying a home can be stressful, which is why you need a close friend and expert in your corner. Could you do it yourself? Technically. But this is likely the most important financial choice you'll ever make, and you deserve a professional making sure it's the right one. Here's why.
The Knowledge Advantage
Want a 4B/2B with an EIK and a W/D? Real estate has its own language, plus a mountain of forms, disclosures, and reports. With over 23 years in this local market, we navigate them to secure a great deal and avoid costly mistakes or delays.
Supercharged Searching
The internet is just the tip of the iceberg. Some properties are never publicly advertised. A local expert knows every neighborhood and can find hidden gems in your price range.
The Power of Negotiation
A great agent writes a purchase agreement that protects you, with enough time for inspections, appraisals, and the contingencies that matter to your situation.
The Network
Working with Reis Real Estate gives you a direct line to trusted mortgage brokers, attorneys, inspectors, stagers, and contractors we've worked with over thousands of transactions. We're in the data, studying comps so you don't overpay, and in your corner every step.
Agent, Broker, or Realtor®: what's the difference?
- Real Estate Agent: licensed by the state to help people buy and sell property, with a state exam and continuing education.
- Real Estate Broker: a step above, with additional education and a higher-level license to own a firm and oversee agents. As Broker/Owner of Reis Real Estate & Co., Inc., Carolyn personally oversees the strategy for every deal the firm handles.
- Realtor®: a member of the National Association of Realtors who follows a strict Code of Ethics. An extra layer of protection for you.
Titles vary by state. In Massachusetts you'll work with licensed Salespeople or Brokers, but the goal is the same: the right home with the right strategy.
What You Need When Buying a House
Your agent can set up searches that update straight from the local MLS. Start by listing your top priorities, which may depend on whether you're looking for a starter home or something else entirely.
Things to consider when shopping
- Price
- Square footage
- Home condition and repairs
- Garage space
- Public transportation access
- Number of bedrooms
- Backyard size and amenities
- Commute and location
- Property value trends
- Real estate taxes
Rank these from most to least important and share the list with your agent. Don't get discouraged if the search takes longer than expected. Only you can decide which property is right, so see plenty of homes before making an offer.
2 to 3 months before buying
- Get a pre-approval letter
- Save searches online
- Start scheduling showings
1 to 2 months before buying
- Find the right home
- Make an offer and negotiate, if needed
- Sign the contract
Closing week
- Schedule the final walk-through
- Set up electric, gas, cable, and internet in your name for closing day
- Review final figures with your lender and closing attorney
- Sign paperwork
- Once the sale is "on record," get your keys!
Phase 1Make an Offer
Found a home you love? Make your offer in writing. It includes details about you, the price you're willing to pay, and a deadline for the seller to respond. We'll prepare it and submit it to the listing agent on your behalf.
Most offers include an earnest money deposit, typically 1% to 2% of the purchase price, which goes toward your down payment and closing costs. If you agree to the sale and later cancel, you typically lose the deposit.
The seller can respond three ways
- Accept: you move on to the next step.
- Reject: submit another offer or move on to another home.
- Counteroffer: the seller changes the price or terms. You can accept, reject, or counter again.
Negotiations can take time. Let us manage them, and don't be afraid to walk away if you can't reach an agreement.
Phase 2Inspection and Appraisal
During the 30 to 45-day escrow period, your lender sets checkpoints for underwriting, likely including an inspection, an appraisal, and requests for more documents. FHA and VA loans can take longer. Any change to your credit or income since pre-approval may need more verification.
Schedule the inspection
Lenders usually don't require one, but you should get an inspection before you sign the purchase and sale agreement. The inspector checks electrical, roofing, appliances, and much more, then gives you a full report. Go through it line by line. If there's a serious issue (like mold or structural foundation cracks), ask the seller to fix it or reconsider the purchase. A small clog is not a major issue.
Most buyers include a home inspection contingency, which lets you back out or negotiate repairs without losing your earnest money if major issues show up.
Get a home appraisal
An appraisal is required for a mortgage, because lenders can't lend more than a home is worth. If it comes in lower than your offer, financing can get tricky. An appraisal contingency can let you back out or negotiate a lower price without losing your deposit. Make sure you understand the terms of yours.
Phase 3Ask for Repairs or Credits
After the inspection, you can ask the seller to:
- Lower the purchase price based on the results
- Give you credits toward closing costs
- Fix the problems before closing
We'll submit your requests to the listing agent. If the seller says no, it's your call. As long as you're within your inspection contingency, you can walk away and keep your earnest money.
Phase 4Prepare for the Move and Stay in Touch
Book a moving company, file your change of address with the post office, and figure out utilities at the new home. If you're renting, give your landlord notice per your lease.
Stay in close contact with your lender as the loan is finalized and send requested documents promptly. Let your lender know your homeowners insurance provider, and keep your agent and attorney in the loop.
Phase 5Close on Your New Home
The morning of closing, or the night before, you'll do a final walkthrough. Make sure any requested repairs were made, the seller has moved out and left nothing behind, there are no pests, and the home's systems are working.
If everything looks good, head to the closing table to sign your paperwork. Depending on the deal, this can take 30 minutes to a few hours. Once it's recorded, the keys are yours!
ConclusionYou have the blueprint. Now you need the team.
Knowledge is only power if you act on it. If you're feeling overwhelmed, or just want an experienced broker in your corner, schedule a strategy call. We'll look at your situation and the market data and build your custom path to ownership. We look forward to handing you the keys to your new home.
Team Reis · Carolyn Reis & Adriana Reis Perry · Reis Real Estate & Co., Inc. · 1149 Pleasant Street, Bridgewater, MA 02324